Repair finance can help motorists manage an unexpected garage bill when a vehicle needs essential work that they cannot comfortably pay for in one lump sum. A failed component, worn brakes, clutch problem, suspension issue or other mechanical fault can create a significant expense, particularly when the repair is unexpected.
However, spreading the cost does not make a repair free. Before agreeing to any payment arrangement, drivers should understand the repair itself, compare quotations, check the finance terms and make sure the repayments fit their wider budget. This guide explains how to approach repair payment plans responsibly while keeping long-term ownership costs under control.
What Is Repair Finance?
Repair finance refers broadly to ways of spreading the cost of vehicle repairs instead of paying the entire garage bill immediately. Depending on the garage and finance provider, this could involve an instalment plan, a credit agreement or another payment arrangement.
MoneyHelper notes that motorists who cannot afford a repair bill may be able to discuss an instalment plan with their mechanic. It also advises drivers to compare options and make sure any repayment arrangement works for their finances. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/blog/car-finance/what-if-i-cant-afford-a-car?utm_source=chatgpt.com))
The exact terms vary between providers, so never assume that all repair payment plans work in the same way. Check whether interest, fees, credit checks or other conditions apply before accepting an offer.
Why Unexpected Car Repairs Can Affect Your Budget
Vehicle ownership involves more than fuel and insurance. Routine servicing, tyres, MOT-related work and repairs all form part of the cost of keeping a car roadworthy.
MoneyHelper’s guidance on vehicle ownership highlights repairs and maintenance as regular costs that should be included when budgeting for a car. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/everyday-money/buying-and-running-a-car/how-to-find-the-right-car-for-your-budget?utm_source=chatgpt.com))
The difficulty comes when an expense arrives earlier or costs more than expected. A driver may have planned for routine servicing but then discover that the vehicle also needs brakes, tyres, suspension components or another major repair.
Having a repair strategy can therefore be just as important as choosing the right vehicle in the first place.
Get the Repair Diagnosed Before Discussing Finance
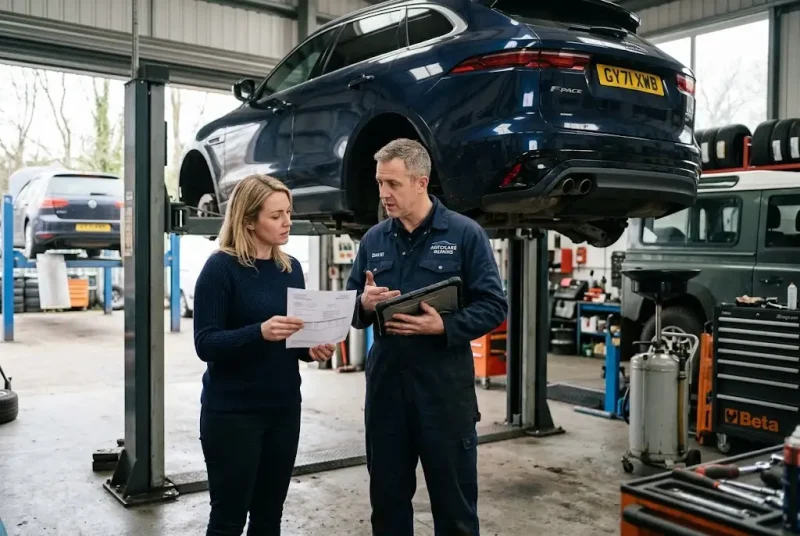
Before thinking about payment arrangements, understand exactly what needs to be repaired. Ask the garage to explain the fault in straightforward terms and provide a written estimate where possible.
A professional garage should be able to explain the proposed work, the parts required and the expected labour involved. If several repairs are recommended, ask which items are essential for safety or roadworthiness and which can reasonably be scheduled for later.
Getting another quotation can also be worthwhile for larger jobs. MoneyHelper recommends visiting more than one mechanic when dealing with unaffordable repair costs so that you can compare prices. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/blog/car-finance/what-if-i-cant-afford-a-car?utm_source=chatgpt.com))
Comparing quotes does not necessarily mean choosing the cheapest garage. Consider the garage’s reputation, the quality of replacement parts, warranty terms and the scope of work included in the estimate.
Check Whether the Repair Is Covered Elsewhere
Before borrowing money for a repair, check whether another source could cover some or all of the cost. Depending on the vehicle and circumstances, this might include a manufacturer warranty, dealer warranty, service contract or relevant insurance policy.
Do not assume that every mechanical problem is covered. Read the relevant terms carefully and ask the provider whether the specific fault qualifies before authorising major work.
If the repair is not covered, you can then compare your available payment options with a clearer understanding of the amount you actually need to fund.
How Repair Payment Plans Can Work
Repair payment plans can vary considerably. Some arrangements may divide the garage bill into several scheduled payments, while others may involve a separate credit provider.
MoneyHelper gives the example of instalment services that may allow repair costs to be repaid monthly, while noting that such arrangements can involve a credit check. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/blog/car-finance/what-if-i-cant-afford-a-car?utm_source=chatgpt.com))
Before agreeing, establish:
- The total amount being financed.
- The number of repayments.
- The amount of each repayment.
- Whether interest is charged.
- Whether arrangement or administration fees apply.
- Whether a credit check is required.
- What happens if a payment is missed.
- Whether early repayment is permitted and on what terms.
A plan that appears affordable because of a small monthly payment can still be expensive if the repayment period is long or additional charges apply.
Compare the Total Cost, Not Just the Monthly Payment
Monthly affordability matters, but it should not be the only consideration. Always calculate the total amount you will pay over the full repayment period.
For example, a shorter arrangement may require larger monthly payments but result in a lower overall cost. A longer arrangement could reduce the monthly burden while increasing the amount paid through interest or fees.
This principle is similar to choosing vehicle finance. Our car finance guide explains why buyers should look beyond monthly repayments and examine the complete cost of borrowing.
When comparing repair finance options, write down the repair cost, deposit if applicable, monthly payment, interest, fees and final amount payable. This makes it much easier to compare two different offers objectively.
Build Repair Costs Into Your Ownership Budget
Repair bills become easier to manage when they are treated as a normal part of vehicle ownership rather than an impossible surprise.
Set aside an amount regularly for maintenance and unexpected repairs. The exact amount depends on your vehicle, mileage, age and financial circumstances, so avoid relying on a generic figure.
Your budget should account for predictable expenses such as servicing, tyres and MOT-related work as well as a separate emergency reserve for unexpected mechanical problems.
MoneyHelper recommends considering insurance, vehicle tax, fuel, repair and maintenance costs when working out whether a car fits your budget. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/everyday-money/buying-and-running-a-car/how-to-find-the-right-car-for-your-budget?utm_source=chatgpt.com))
Maintenance Plans Can Reduce Financial Surprises
Preventive maintenance is one of the best ways to improve ownership planning. Following the vehicle manufacturer’s recommended servicing schedule can help identify developing problems before they become more serious.
Keep records of servicing, repairs and replacement parts. A maintenance history helps you understand what has already been completed and what may be approaching its service interval.
Tyres deserve particular attention because they are both a maintenance expense and a safety-critical component. Regularly checking tyre condition and arranging professional replacement when necessary can help prevent avoidable problems. Our tyre services guide explains more about tyre fitting, replacement and preventive maintenance.
Good maintenance cannot eliminate every unexpected repair, but it can make vehicle ownership more predictable.
Ask the Garage the Right Questions
Before authorising expensive work, ask the garage to explain the repair clearly. You should know what has failed, why the repair is recommended and what could happen if the work is delayed.
Useful questions include:
- What exactly has failed?
- Is the repair essential for safety?
- What parts will be replaced?
- Are the parts new, used or refurbished?
- How much will labour cost?
- Is VAT included in the estimate?
- Is there a warranty on the repair?
- Are there other issues that should be addressed soon?
- How long will the vehicle be off the road?
- Can the garage provide a written quotation?
For example, consumer guidance from nidirect states that garages should use reasonable skill and care and, where no price has been agreed beforehand, charge a reasonable amount. It also advises motorists to clarify what they want repaired and ask about the expected cost and completion time. ([nidirect.gov.uk](https://www.nidirect.gov.uk/articles/car-repairs?utm_source=chatgpt.com))
Know When Repair Finance May Make Sense
Spreading a repair bill may be reasonable when the vehicle is otherwise reliable, the repair is necessary and the repayment comfortably fits your budget.
It can be particularly useful when an essential repair cannot reasonably be postponed and paying the full amount immediately would leave you unable to cover other important household expenses.
However, borrowing should not automatically be used for every repair. If a vehicle has reached a point where major faults are appearing repeatedly, adding more debt may not solve the underlying financial problem.
MoneyHelper suggests considering whether continued repair spending makes sense when repair costs become significant. In some situations, replacing the vehicle or using another transport solution may be financially more sensible in the long term. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/blog/car-finance/what-if-i-cant-afford-a-car?utm_source=chatgpt.com))
When Repair Finance May Not Be the Best Option
There are several situations where borrowing for a repair deserves extra caution. If the vehicle requires frequent major repairs, has very high mileage or has a low remaining market value, compare the cost of repair with the vehicle’s overall value and expected future reliability.
Consider the likely cost of keeping the vehicle for another year rather than looking only at today’s garage bill. If several expensive repairs are likely to follow, a repair payment plan could simply postpone a larger financial decision.
On the other hand, replacing a vehicle also creates costs. A new purchase may require a deposit, finance payments, insurance changes and other expenses. Therefore, compare both scenarios rather than assuming either repairing or replacing is automatically cheaper.
What If You Cannot Afford the Repair?
If you cannot comfortably pay for essential work, speak to the garage before making assumptions about what is possible. Ask whether the work can be prioritised, whether a staged repair is practical or whether an instalment arrangement is available.
MoneyHelper specifically recommends speaking with the mechanic about possible instalment plans and comparing repair prices. It also notes that drivers have a responsibility to ensure their vehicle remains safe to drive. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/blog/car-finance/what-if-i-cant-afford-a-car?utm_source=chatgpt.com))
Do not continue driving a vehicle that is unsafe simply because you cannot currently afford the repair. If necessary, arrange alternative transport while you work out the safest and most affordable solution.
Keep Repair Finance Separate From Existing Car Finance
If your vehicle is already subject to PCP or HP finance, an unexpected repair creates another financial commitment. Avoid assuming that adding another payment will automatically fit your budget.
Review your existing monthly obligations first. Our used cars buying guide explains why ownership planning should include maintenance records, running costs and potential future expenses when assessing the affordability of a vehicle.
If you are already struggling with vehicle finance payments, contact the finance provider before missing payments. MoneyHelper advises speaking to the finance company early because there may be arrangements available to help manage payment difficulties. ([moneyhelper.org.uk](https://www.moneyhelper.org.uk/en/everyday-money/buying-and-running-a-car/if-you-cant-afford-your-car-payments?utm_source=chatgpt.com))
Keep Records of Every Repair
Once the work is completed, retain the invoice and details of the repair. A complete maintenance record can help you track future servicing requirements and may support the vehicle’s resale value later.
Record the date, mileage, work completed, parts replaced and amount paid. If a warranty applies to the repair or replacement component, keep those documents with the invoice.
Good records also help another garage understand the vehicle’s history if you move to a different service provider in the future.
Repair Finance Should Support, Not Replace, Financial Planning
Repair finance can be useful when an essential vehicle repair creates a temporary cash-flow problem, but it should form part of a wider ownership strategy. The most responsible approach is to understand the repair, compare garage quotations, check available coverage and then evaluate payment options.
Before accepting a payment plan, compare the total repayment cost with the immediate repair price and consider whether your monthly budget can comfortably support the additional commitment.
For longer-term ownership, combine emergency savings with regular maintenance planning. This can reduce the need to borrow whenever a predictable expense appears.
Ultimately, the goal is not simply to find a way to pay today’s garage bill. It is to keep the vehicle safe, manage ownership expenses sensibly and avoid turning one unexpected repair into a much larger financial problem.
When approached carefully, repair finance can provide useful breathing room. The key is to treat it as a financial tool rather than a substitute for proper vehicle maintenance, realistic budgeting and informed ownership decisions.