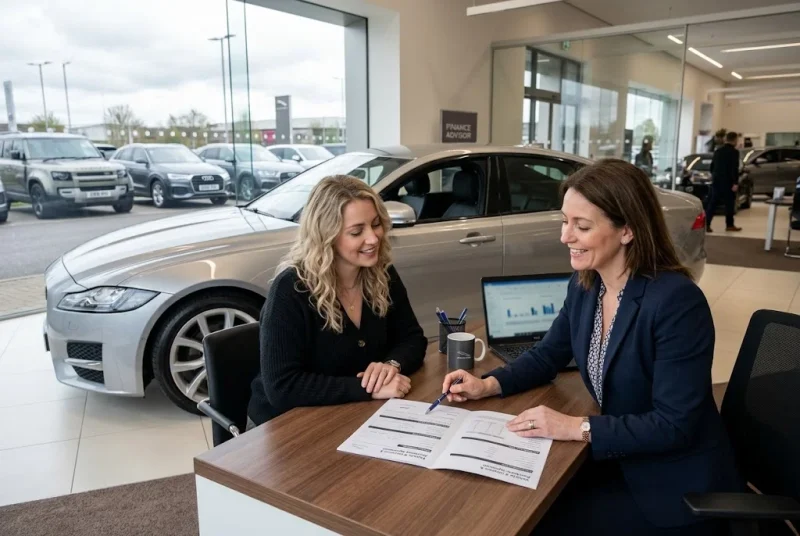
Car finance can make buying a vehicle more manageable by allowing you to spread the cost through an initial deposit and regular payments. However, choosing a finance agreement should involve more than finding the lowest advertised monthly repayment. The deposit, interest, contract length, final payment, mileage allowance and total amount payable can all affect the real cost of your vehicle.
Whether you are considering a used car from a dealership or a newer vehicle, understanding the main financing options can help you make a more confident decision. This guide explains how vehicle finance works in the UK, how PCP and HP differ, what to check before signing and how to build finance into a realistic ownership budget.
What Is Car Finance?
Car finance allows you to pay for a vehicle over an agreed period instead of paying the entire purchase price upfront. Depending on the arrangement, you may make a deposit followed by fixed monthly payments, with ownership either transferring at the end or remaining conditional on a final payment.
The two common dealership finance options discussed by MoneyHelper are Personal Contract Purchase (PCP) and Hire Purchase (HP). A PCP normally has lower monthly payments because part of the vehicle’s expected future value is deferred until the end. HP generally spreads the full financed amount across the agreement, followed by a small option-to-purchase fee, so monthly payments are usually higher than PCP.
Other borrowing options can include personal loans or paying with savings. The best choice depends on your budget, expected ownership period and preference for outright ownership or lower monthly payments.
How Car Finance Fits Into Your Budget
Before approaching a dealership, establish how much you can comfortably afford each month. However, avoid treating the monthly payment as your entire vehicle budget.
Car ownership also involves insurance, fuel, servicing, tyres, MOT-related expenses, repairs and other running costs. MoneyHelper recommends considering these costs alongside finance repayments when working out what you can afford.
A practical budget should therefore include:
- Initial deposit
- Monthly finance payment
- Insurance
- Fuel or charging costs
- Servicing and routine maintenance
- Tyres and replacement parts
- MOT-related expenses where applicable
- Unexpected repair costs
Leaving some spare money after your regular commitments can make vehicle ownership more sustainable. A finance agreement that consumes nearly all your available monthly budget may become difficult to manage if your circumstances change.
PCP Car Finance Explained
Personal Contract Purchase, commonly called PCP, is a popular form of vehicle finance. You normally pay a deposit followed by monthly payments over an agreed period. A larger final payment, often called a balloon payment, is deferred until the end if you want to purchase the vehicle outright.
Because the monthly payments do not normally cover the entire vehicle value, PCP payments can appear more affordable than HP payments for a similar car. However, the lower monthly figure does not necessarily mean the agreement is cheaper overall.
What Happens at the End of PCP?
At the end of a PCP agreement, you generally have several choices. You can pay the final balloon payment and keep the vehicle, return it subject to the agreement’s conditions, or potentially move into another finance agreement.
If you return the vehicle, mileage restrictions and fair-wear-and-tear requirements can become important. Going beyond the agreed mileage or returning a vehicle with chargeable damage may result in additional costs.
This makes it important to estimate your annual mileage realistically before signing. Choosing an artificially low mileage allowance to reduce payments can create problems later.
HP Finance Explained
Hire Purchase, or HP, is a more straightforward structure for buyers who want to work towards ownership through regular payments. You generally pay a deposit, followed by monthly instalments covering the vehicle’s financed value plus interest. An option-to-purchase fee may apply at the end of the agreement.
Unlike PCP, HP normally does not have a large balloon payment at the end. Once the required payments and applicable final fee have been completed, ownership transfers according to the agreement.
The trade-off is that HP payments can be higher because you are financing more of the vehicle’s value through the regular instalments. However, buyers who intend to keep the car may prefer the simplicity of this structure.
Car Finance: PCP vs HP
PCP and HP can both be useful, but they suit different priorities.
PCP May Suit You If
- You want lower monthly payments compared with financing the full vehicle value through HP.
- You may want flexibility at the end of the agreement.
- You are comfortable managing a possible final balloon payment if you want to own the car.
- Your expected annual mileage is reasonably predictable.
HP May Suit You If
- You want a straightforward route towards ownership.
- You prefer not to have a large balloon payment at the end.
- You expect to keep the vehicle after completing the agreement.
- You are comfortable with potentially higher monthly repayments.
MoneyHelper notes that PCP can provide lower monthly payments, while HP is simpler and generally leaves you with the vehicle after completing the agreement. The right choice depends on your circumstances rather than one option being universally better.
Look Beyond Monthly Repayments
A monthly payment is only one part of a finance agreement. Before signing, calculate the total amount you will pay over the full term.
For example, a deal with a low monthly repayment may have a larger deposit, longer term or substantial final payment. Another agreement could have higher monthly payments but a lower overall cost. Comparing only the monthly figure can therefore produce a misleading impression of affordability.
Check the deposit, monthly repayment, APR, contract length, final payment, fees and total amount payable. MoneyHelper specifically recommends checking these elements when agreeing PCP or HP finance.
Understand Your Mileage Allowance
Mileage is particularly important when considering PCP. Your agreement normally includes an annual mileage allowance, and exceeding the agreed limit can result in additional charges when the vehicle is returned.
Think about your real driving habits before agreeing to a figure. Include commuting, family journeys, holidays and regular longer trips rather than relying on an optimistic estimate.
If your circumstances change during the agreement, contact the finance provider rather than simply assuming the original mileage allowance will remain suitable. Planning ahead can help avoid unnecessary costs at the end of the contract.
Consider the Total Cost of Ownership
Finance payments are only one part of vehicle ownership. A car that looks affordable on finance may still be expensive to run.
For example, a larger vehicle may have higher insurance, fuel and tyre costs. An older used vehicle could have a lower purchase price but require more maintenance. These factors should be considered before choosing the finance agreement.
Our used cars buying guide explains how vehicle history, maintenance records, resale value and ownership planning can affect the overall buying decision.
Tyre costs should also form part of your ownership budget. Regular checks and professional replacement can help you plan for an expense that is sometimes overlooked when buyers focus only on the purchase price. Our tyre services guide covers tyre fitting, replacement and maintenance in greater detail.
Car Finance and Credit Checks
Finance applications normally involve a credit assessment. The exact process and lending decision depend on the provider and your circumstances.
Before making several applications, understand what type of credit search may be involved and make sure the information on your application is accurate. It can also be useful to review your finances beforehand so that you have a clear picture of existing commitments.
Do not assume that being offered finance means the agreement is affordable. The lender’s decision and your personal budget are two different considerations.
Questions to Ask Before Signing
Never sign a finance agreement simply because the monthly payment appears manageable. Ask the dealer or finance provider to explain anything you do not understand.
- What is the total amount payable?
- How much is the deposit?
- What is the APR?
- How long is the agreement?
- What are the monthly repayments?
- Is there a final balloon or option-to-purchase payment?
- What mileage allowance applies?
- Are there excess-mileage charges?
- What are the rules regarding vehicle condition?
- Are servicing or maintenance included?
- Are there additional fees?
- What happens if I want to settle the agreement early?
MoneyHelper’s guidance similarly recommends checking the deposit, payments, interest, APR, contract length, mileage allowance, wear-and-tear rules and other fees before agreeing to PCP or HP.
Can You End Car Finance Early?
There may be circumstances in which you want to settle or end a finance agreement before its scheduled completion. For example, your financial situation may change or you may want to replace the vehicle.
Do not assume that ending a contract early is cost-free. MoneyHelper advises consumers to understand the conditions and costs before deciding to end PCP or HP early. Depending on the circumstances, you may be able to request a settlement figure or use other rights available under the agreement.
If you are struggling to make payments, contact the finance provider as early as possible rather than waiting until payments are missed. A discussion about your circumstances may provide options that are not available after the account falls into arrears.
Build Car Finance Into Long-Term Ownership Planning
A vehicle finance agreement can last for several years, so think beyond the first few months. Consider whether your income, mileage and household expenses are likely to change.
It is also worth considering what you want to happen when the agreement ends. With PCP, decide whether you would realistically want to make the final payment, return the vehicle or move to another vehicle. With HP, consider whether completing the regular payments fits your long-term plans.
Good ownership planning also includes future maintenance. If an unexpected mechanical problem creates a significant bill, some drivers may investigate repair finance or other payment arrangements. Any additional borrowing should be assessed separately from the original vehicle finance and compared on its total cost.
Shop Around Before Choosing a Deal
Do not assume the first finance package offered by a dealership is automatically the best option. Compare the vehicle price, finance structure and total cost before committing.
When researching vehicles online, our AutoTrader UK buying guide explains how to compare vehicle listings, dealership information and purchase options more systematically.
It is also useful to separate the vehicle negotiation from the finance discussion where possible. Understanding the cash price and finance cost independently can make it easier to see what you are actually paying for the car and what you are paying for credit.
When Car Finance May Not Be the Right Choice
Finance is not automatically the best option for every buyer. If you have sufficient savings, paying cash can avoid interest and give you immediate ownership, although you should still retain an emergency reserve.
A less expensive vehicle may also be a better solution if the finance payment would place too much pressure on your monthly budget. Choosing a car that costs less can reduce not only the finance requirement but potentially the associated insurance, fuel and maintenance expenses.
The important question is not simply whether you can obtain finance. It is whether the complete cost of the vehicle fits comfortably within your financial plans.
Make Car Finance Part of a Complete Buying Strategy
The strongest vehicle purchase decisions combine finance planning with careful vehicle research. Start with the car you actually need, establish an affordable ownership budget and then compare financing options.
Review the vehicle’s history and condition, investigate the seller and consider likely maintenance costs. Once you have identified a suitable car, compare PCP, HP and other relevant financing options using the total amount payable rather than focusing solely on monthly repayments.
Car finance can be a useful tool when the agreement matches your budget and ownership plans. It becomes much easier to use responsibly when you understand the numbers, know what happens at the end of the contract and leave enough financial room for the ordinary costs of running a vehicle.
Taking time to compare financing options before signing can give you greater ownership confidence and help ensure that the vehicle remains affordable throughout the agreement, not just on the day you drive it home.